Mir
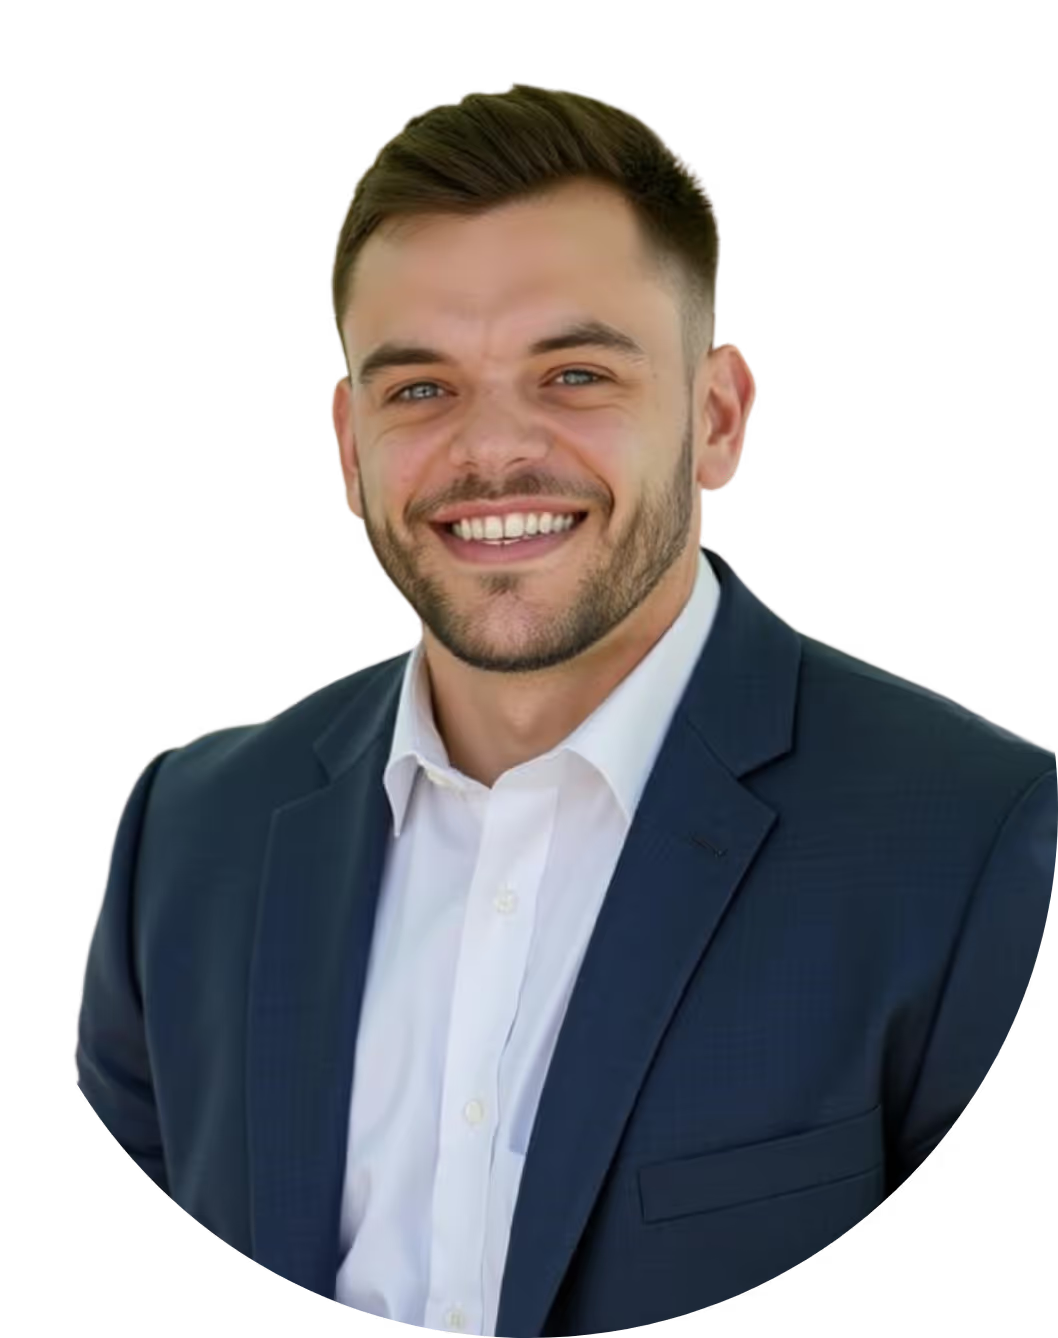
Hi, I'm Pierce Hyldahl
Passionate about helping individuals and business owners build, protect, and grow their wealth. Let's create a plan that gives you confidence for the future.
Who Am I?
I’ve seen firsthand the meaningful impact thoughtful financial guidance can have on individuals and families. Growing up, I watched my father use his experience as a financial advisor to make a genuine difference in people’s lives, which inspired me to follow in his footsteps as a third-generation financial advisor and continue serving the next generation.
My approach is centered on understanding what matters most to each client and helping them build a financial strategy around those goals. I specialize in tax-efficient retirement planning, portfolio management, and insurance strategies for individuals, families, and business owners.
I’ve continued to expand my education through advanced studies in retirement planning and financial services at The Wharton School, as well as behavioral finance at Columbia University. I’m grateful to be part of a firm that shares my belief that clients and their goals should always come first.
A lifelong New Jersey resident, I now live in Annandale with my wife, Julia, our son, Arthur, and our French Bulldog, Mochi. Outside of work, I enjoy spending time with family, lifting weights, cycling, practicing martial arts, basketball, and playing the drums.
Who Are My Ideal Clients?
The people I serve best.
By Profession
-
Business Owners
Building, growing, and protecting what they've built.
-
Skilled Tradesmen
Hardworking individuals and families building a better future.
-
Attorneys
Busy professionals navigating complex financial decisions.
-
Sales Professionals
Driven, goal-oriented professionals focused on growth and success.
By Character
-
Coachable
Open to guidance and committed to continuous improvement.
-
Honest
Values integrity, transparency, and doing the right thing.
-
Relationship-Focused
Values long-term relationships and mutual trust.
-
Goal-Oriented
Focused on building a secure future for themselves and their families.
Credentials & Expertise
Tailored Financial Solutions for Your Life Goals.
Early Retirement Roadmap for Tech Professionals
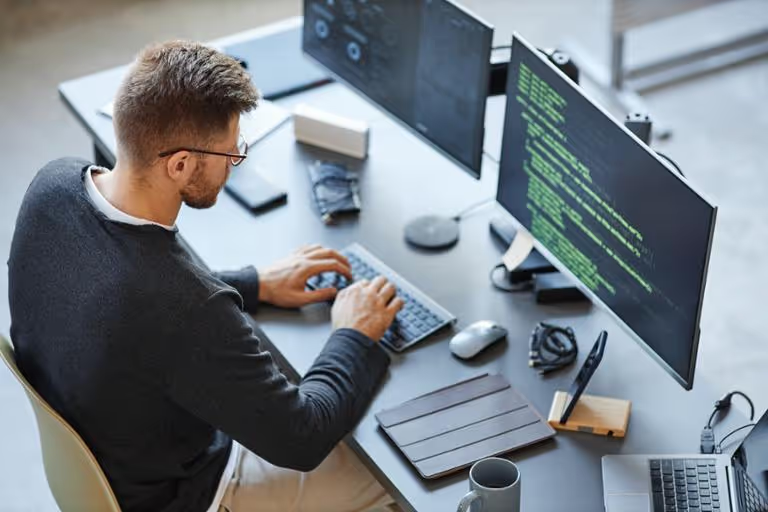
Partnered with a couple in their mid-30s from the Bay Area to accelerate their retirement timeline from 65 to 55. Optimized Roth conversions, mega backdoor contributions, and equity compensation strategies to build a $2.8M nest egg projection while minimizing taxes.
Family Protection Overhaul for New Parents
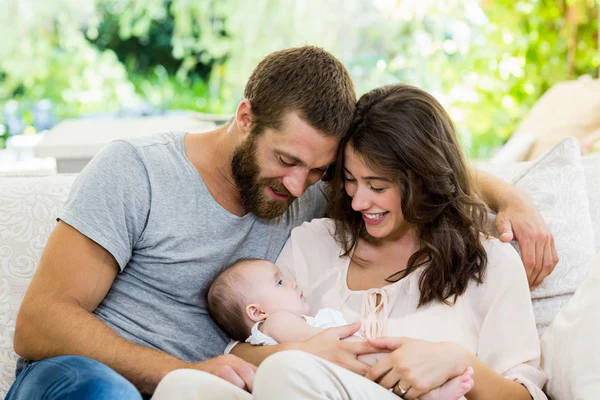
Conducted a full insurance review for a young family after their first child. Upgraded term life coverage, added critical illness riders, and implemented disability income protection—all while reducing total premiums by 18% through better carrier matching and policy optimization.
Risk-Adjusted Portfolio Rebuild During Volatility
Worked with a high-net-worth client to restructure their investment portfolio amid 2022 market downturns. Shifted to a more diversified, low-volatility allocation (including bonds, dividend aristocrats, and alternative assets) that preserved capital and positioned for stronger recovery gains.
Secure Retirement Transition for Retirees
Assisted a recently retired executive couple in shifting from accumulation to distribution phase. Designed a tax-efficient withdrawal plan combining Social Security timing, Roth ladder conversions, and annuity options to provide steady monthly income with minimal market risk exposure.
Disability Income Protection: The "Safety Net" Strategy
Partnered with a high-earning medical professional to implement a private disability income policy. By layering this over their employer-provided coverage, we filled a 40% income gap, ensuring their family's lifestyle and mortgage remain secure even if they are unable to work.
Long-Term Care Planning: Preserving the Estate
Developed a hybrid Long-Term Care strategy for a couple in their late 50s. By leveraging a policy with a "death benefit if not used" feature, we protected their $1.5M investment portfolio from being depleted by potential nursing care costs while maintaining the asset for their heirs.
Relocating Assets for Tax-Free Retirement Income
Successfully transitioned a client’s heavily weighted taxable brokerage account into a diversified mix of tax-advantaged vehicles. By strategically "relocating" these assets over a three-year period, we saved the client an estimated $12,000 annually in future retirement income taxes.
Additional Portfolio Highlights
Strategic Roth Conversions: Identified and executed Roth conversion opportunities during lower-income years to lock in historically low tax rates.
Volatility Guidance: Provided steady, data-driven market guidance through every major volatility cycle, preventing emotional selling and capturing recovery gains.
Collaborative Planning: Coordinated holistic strategies directly with clients' CPAs and estate attorneys to ensure tax and legal alignment.
Income Optimization: Designed distribution plans that perfectly sync Social Security timing with pension payouts for maximum cash flow efficiency.
Early Retirement Roadmap for Tech Professionals
Partnered with a couple in their mid-30s from the Bay Area to accelerate their retirement timeline from 65 to 55. Optimized Roth conversions, mega backdoor contributions, and equity compensation strategies to build a $2.8M nest egg projection while minimizing taxes.
Secure Retirement Transition for Retirees
Assisted a recently retired executive couple in shifting from accumulation to distribution phase. Designed a tax-efficient withdrawal plan combining Social Security timing, Roth ladder conversions, and annuity options to provide steady monthly income with minimal market risk exposure.
Family Protection Overhaul for New Parents
Conducted a full insurance review for a young family after their first child. Upgraded term life coverage, added critical illness riders, and implemented disability income protection—all while reducing total premiums by 18% through better carrier matching and policy optimization.
Disability Income Protection: The "Safety Net" Strategy
Partnered with a high-earning medical professional to implement a private disability income policy. By layering this over their employer-provided coverage, we filled a 40% income gap, ensuring their family's lifestyle and mortgage remain secure even if they are unable to work.
Risk-Adjusted Portfolio Rebuild During Volatility
Worked with a high-net-worth client to restructure their investment portfolio amid 2022 market downturns. Shifted to a more diversified, low-volatility allocation (including bonds, dividend aristocrats, and alternative assets) that preserved capital and positioned for stronger recovery gains.
Relocating Assets for Tax-Free Retirement Income
Successfully transitioned a client’s heavily weighted taxable brokerage account into a diversified mix of tax-advantaged vehicles. By strategically "relocating" these assets over a three-year period, we saved the client an estimated $12,000 annually in future retirement income taxes.
Trusted by Those I Serve
60+ reviews and growing